

Why Growing Revenue Doesn't Solve Your Cash Flow Problems
As your business grows, managing finances becomes increasingly important, especially cash flow management and cash flow forecasting. Because, unfortunately, your business can look well on paper with growing revenue but there might be underlying cash flow problems that stay hidden until it’s too late.
I was talking with a couple of prospects recently and this was the problem they were facing. Their revenue continues to grow and they have clients, but they are constantly cash flow constraint and living month to month.
Sadly, this is the reality many business owners are facing, and I thought that this week I’d like to spend some time talking about it and sharing some of the reasons behind it, and also a solution I recommend.
If this hits closer to home than you want to admit, this is for you.
Why Growing Revenue Doesn't Solve Your Cash Flow Problems
2 Reasons You Might Have Cash Flow Problems Even With Growing Revenue
Revenue vs. Cash Flow
Before we dive into the reasons why your business might be experiencing cash flow problems, let’s make sure we know the terms.
Yes, I know you are an established business owner, but you’ll be surprised how many people don’t have a clue that there’s a difference between the two.
Investopedia defines revenue as “the total money a company earns from selling goods or services before expenses are subtracted.”
Cash flow, on the other hand, “represents the movement of money in and out of a company, reflecting its liquidity position and operational efficiency.”
Feel free to check the Investopedia articles to familiarize yourself with these terms more if you need it. But remember to come back here because we are about to dive into the interesting part.
2 Reasons You Might Have Cash Flow Problems Even With Growing Revenue
The prospects I talked with had the right idea. They wanted someone to look at their finances and figure out what was going on.
In general, there are two main reasons why your cash flow is negative even when your revenue and sales are increasing.
Period of Investment
The first reason is the most intentional one and if you are going through this, you would know why your cash flow is negative.
What I’m talking about is a period of investment. You might be at a stage where your business is expanding intentionally, and you are investing in assets that will pay you in the near future or in the long term. Maybe you’re buying new equipment or upgrading the old one. Maybe you’re opening a second location or bringing in new employee(s).
In this case, you probably have good cash flow management and forecasting, even if currently your cash flow is negative.
If you are in this period, what matters is for you to manage the cash flow properly and ensure you start seeing the increased revenue and positive cash flow as per your forecast.
Poor Financial Management
Ok, this one probably hurts but it is what it is.
I see two types of poor financial management with clients and prospects:
Expenses are too high compared to revenue
You’ll be surprised how often this happens. Even before hiring and adding payroll to their expenses, many businesses end up accumulating various paid subscriptions, services, and products.
Yes, when you are in business, you need to spend money to make money. But if your expenses are too high for a prolonged period of time, you’ll run into problems. Even when your revenue is growing.
It’s always a good idea to keep track of your expenses to make sure you periodically prune them, renegotiate them, and eventually refine your pricing, so your revenue keeps up with the increase in expenses.
Timing difference between accounts payable and accounts receivable cycles
The other big reason under the umbrella of poor financial management is a consistent gap between the accounts payable and accounts receivable cycles.
This one usually impacts businesses that offer payment options or big ticket items. And the cash flow problem occurs when the vendors and suppliers consistently need payment before cash is collected from clients and customers.
So, what do you do about it and how can you implement better cash flow management?
Profit First Framework
If you are dealing with a persistent cash flow problem as your business revenue is growing and it’s not due to an intentional period of investment, I’d highly recommend contacting an expert to help you figure things out and stabilize your cash flow.
And while you’re doing this, my other recommendation is to implement the profit first framework in your business. It’s one of my favorite financial management and cash flow management tools and I advise all my clients to establish this process as part of their financial management.
What is profit first?
This is not my process or idea. It’s actually something Mike Mihalowicz came up with thanks to watching a commercial about portion control for weight loss.
He had a realization that if portion control works for weight loss, it should work for running a business.
So, what he recommends is for us, business owners, to portion our revenue and for this purpose we need at least 5 accounts:
Income account where all the revenue “lands”
Profit account for profit allocation
Owner’s compensation account for what you want to pay yourself
Tax account for what Uncle Sam needs
Operating expenses for the money you need to spend to run your business
For my fellow Canadians, I’d add HST/GST account where you should allocate the HST/GST you are charging.
And this is the allocation Mike recommends based on your revenue range:
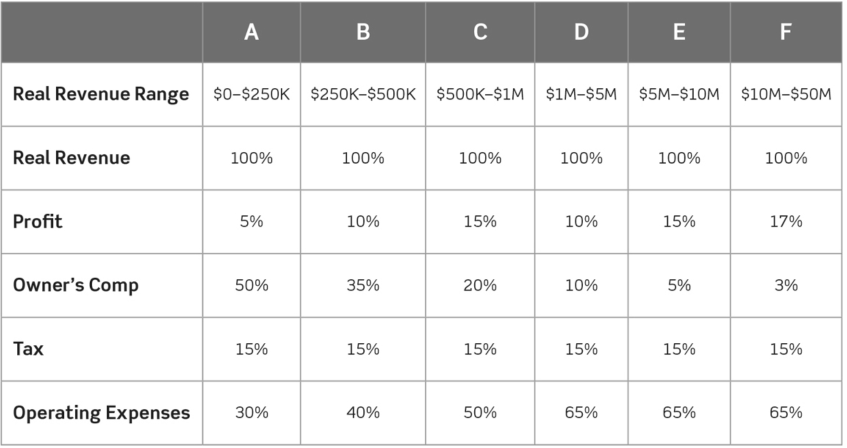
Again, a note for fellow Canadians, you might need to adjust the tax percentage to reflect our overtaxed reality.
I’d highly recommend reading the Profit First book, btw. No affiliation. Just a must read for any business owner and then must implement, of course.
Mike goes deeper into other types of accounts you might want to open as your business grows and depending on the business you have. For example, if you provide pre-paid services like me, you might want to have a so-called Drip account for cash you received but haven’t delivered the service yet.
Why use it?
Why am I singing praises for a system that’s not mine?
Because this is truly a life-changing approach to cash flow management for any business.
See, if the prospects I talked with had this system in place, they would be able to see where the cash flow problem is. Are they spending too much on salaries? Or is it interest on loans? Or maybe the other expenses are the culprit?
Implementing a profit first system as soon as possible allows you to start managing your cash flow better and streamlining your business in the process.
It also gives you great visibility into where you stand today. You just need to log into your online or mobile banking and see that you have enough money in the owner comp account to take a 2-week vacation. In other words, you can stop working and brining revenue and still pay yourself for 2 weeks.
This is an example of how I do a bit of monthly cash flow forecasting as well:
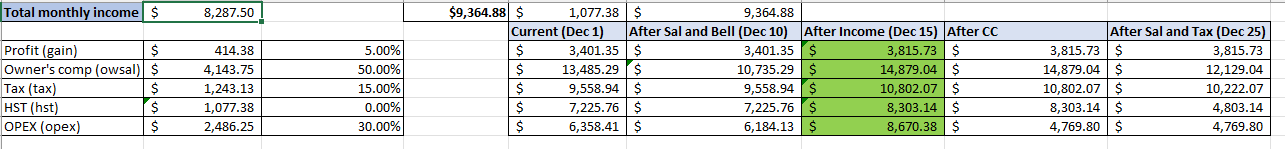
You can see from the above snapshot that I would have had a bit over $10K in my owner’s comp account. I was paying myself $2,750 every two weeks, so $10K meant that I could take 6 weeks off without any new revenue and still get paid.
However, if you look at my expenses account, my monthly expenses were on average $3,400 and I would have had a bit over $4,700 in my account. So, it would have been wiped out in a month of no revenue. Not good, btw.
Cash Is King
Yes, revenue growth matters. Having happy clients who come back and/or refer others matters. But so does cash flow.
Revenue is one part of your business, and it usually indicates how well your marketing and sales processes work. Well, partially. Because it just shows one part of the equation and the health of your business.
I know we are approaching the end of the year and it’s all hands on deck to finish 2026 strong. Yet, I would highly encourage you, especially if you have read the article up to this point, to implement the profit first system in your business as soon as possible. Even if you are not facing any cash flow problems. Or should I say, especially if you are not facing cash flow problems. Because the best time to get batter at cash flow management and forecasting is while things are going well for your business.
And if you’d like to continue the conversation and get the chance to ask me questions on this or any other topic, join the Visionary Founders Club. It’s a free community for aspiring and established business owners who want to build successful businesses and meaningful lives. This is the link to join. I’d love to see you there.
Until next week when I’ll be diving into a problem all of us seem to face – too many ideas and too little time.
Remember to cherish the simple moments.